Where the Tip Lands: Tracing Card Gratuities Through a Bristol Café's Till
Photo: U.S. Army 405TH-AFSB by Rabia Coombs, Public domain, via Wikimedia Commons
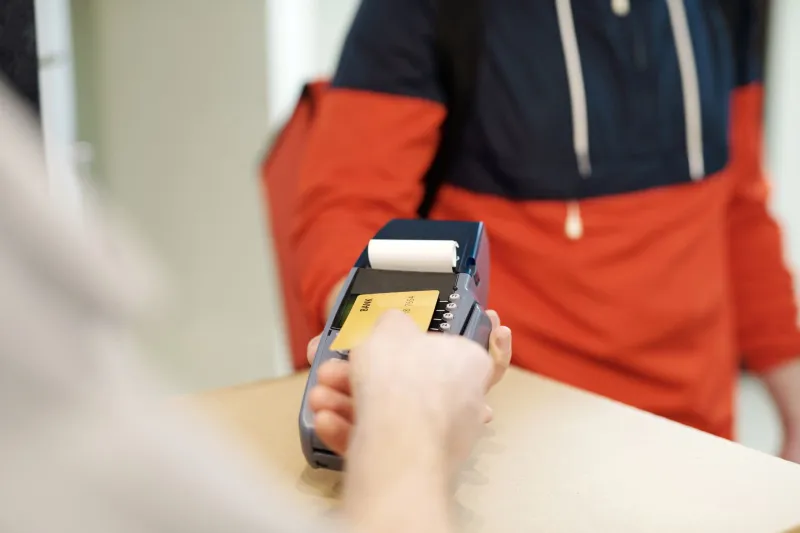
A customer taps a preset percentage, the terminal beeps, and the tip is folded into the card total. For the customer, the transaction is finished. For the Bristol café, the work has only started: the gratuity must be separated from the sale, settled with the rest of the card batch, accounted for correctly and then allocated under a policy that staff can understand. The screen is the visible part of that process. The contract, the payroll route and the record-keeping sit behind it.
The screen is only the beginning
When a café enables tipping on its card terminal, the tip usually becomes part of the authorised transaction rather than a separate payment. That matters for reconciliation. The amount that arrives in the merchant account is the total of sales plus gratuities, less any processing charges and adjustments. A bookkeeper therefore needs a reliable way to identify the tip element, not merely a daily total that blends tips with coffee and sandwiches.
For a Bristol independent, the practical test is simple: can you show, from the terminal report and the merchant statement, how much of a given day's card receipts was gratuity? If the answer depends on memory or a rough percentage, the system is too thin. Most modern terminals and payment dashboards can produce a tip summary, but the feature must be switched on and the report exported before the batch is closed. The café's accounting routine should treat that summary as a separate record, not as an afterthought.
What the 2023 Act asks of an employer
The Employment (Allocation of Tips) Act 2023 changed the framework for gratuities in Great Britain. Its provisions came into force in 2024, and by 2026 they are part of ordinary payroll governance for hospitality businesses. The central principle is that qualifying tips must be allocated fairly, and the employer must have a written policy explaining how that happens. Workers should be able to see the policy and understand the basis on which tips are shared.
Card gratuities paid through the employer's terminal are generally qualifying tips. The employer must ensure they are allocated and paid within the statutory timeframe, which is one month after the end of the month in which the customer paid the tip. Records must be kept. The detail matters for a café with a mix of full-time staff, part-time weekenders and agency workers, because the policy has to cover the people who do the work, not just the names on the rota.
The Act does not prescribe a single split. A café can use points, hours, role-based weighting or an equal share, provided the approach is fair and documented. What it cannot do is treat card tips as general revenue, absorb them into the business without a clear policy, or leave staff guessing. The gratuity screen may ask the customer for a tip, but the employer remains responsible for what happens next.
Tronc and payroll are different routes
A Bristol café will usually choose between running tips through payroll or through a tronc. In a payroll route, the tip is treated as pay and subjected to the usual tax and National Insurance treatment. In a tronc, an independent troncmaster distributes tips, and the tax treatment can differ, particularly where the tronc qualifies as independent. The tronc route is not a loophole; it is a structure with its own records, responsibilities and deadlines.
The choice affects staff take-home pay, employer administration and the evidence the café can produce if queried. It also affects how card tips are handled at the till. If the terminal adds a tip to the card total, the funds enter the business's merchant account before they are distributed. The café must therefore bridge the gap between settlement and allocation, and it must keep the tip record separate from ordinary sales. A small café can do this with a spreadsheet and a monthly check; a larger operation may need its EPOS and payroll systems to speak to each other.
Do processing fees touch the tip?
Processing charges are usually calculated on the total transaction value, and that total can include the gratuity. Whether the café absorbs the charge on the tip or passes it through in some way depends on its merchant agreement and its tipping policy. Some acquirers offer tip-specific reporting but do not reduce the fee on the tip element; others may have different arrangements. The contract wording should be checked rather than assumed.
The commercial effect is modest per transaction but visible over a year. A café taking £1,000 a week in card tips is not dealing in rounding errors. If the processing charge applies to the full amount, the café should know the annual cost and decide whether to absorb it, adjust its tip split or renegotiate. Refunds and chargebacks add another layer: if a customer disputes a bill that included a tip, the reversal can remove the gratuity along with the sale. The café's policy should say how that is reflected in the tip record, so staff are not asked to repay money that was never allocated to them.
Prompt design is a commercial decision
A gratuity screen can invite a tip with preset percentages, a custom amount or a simple yes-or-no prompt. Each design carries a message. Preset percentages can increase uptake, but they can also make customers feel steered. A clear no-tip option protects the customer's choice and reduces friction at the counter. The café should avoid language that implies a tip is compulsory, and it should distinguish a discretionary gratuity from a compulsory service charge.
For staff, the screen should be explained before the first shift. A short induction can cover three points: what the customer is being asked, where the money goes, and when it is paid out. That prevents the terminal from becoming a source of quiet resentment. A barista who understands that the tip is recorded separately and distributed under a written policy is better placed to answer a customer's question than one who has been told only to tap the next button.
A straightforward monthly audit
A Bristol café can keep the process transparent with a monthly check. Reconcile the terminal tip report against the merchant statement and the sales ledger. Confirm that the tip total has been allocated under the written policy and paid within the statutory period. Check that the tronc or payroll record matches the amount distributed. Review the prompt wording and the no-tip option, and ask staff whether the explanation still makes sense. Finally, keep the evidence together: policy, reports, allocation records and payment dates.
The gratuity screen takes a second of a customer's time. The system behind it should be able to answer a simple question for years: where did that tip land, and who decided?