What Travels With the Shop: Card Contracts in a Bristol Business Sale
Photo: independent shop counter card payment terminal handover documents Bristol England, via st2.depositphotos.com
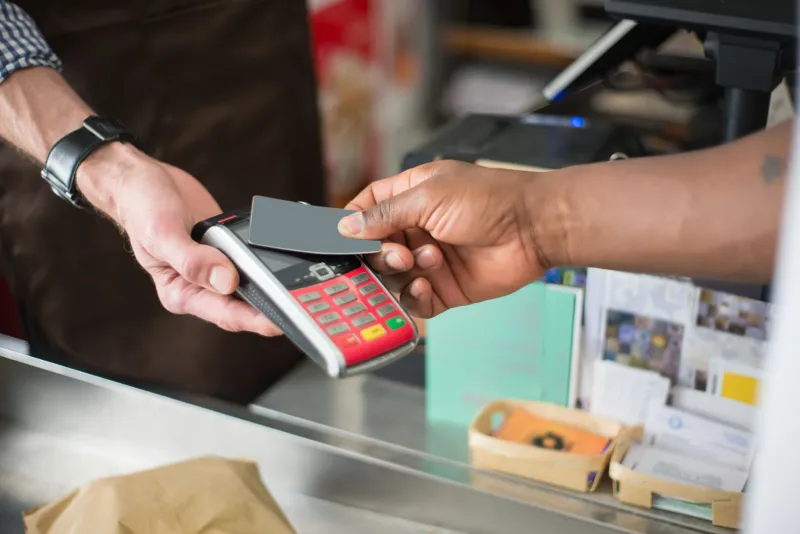
A card terminal on the counter can look like part of the fixtures and fittings. In practice, it is usually the visible end of a set of contracts that were never designed to be passed around like a set of shop keys. For a Bristol independent buying or selling a business in 2026, the card-processing arrangements deserve the same scrutiny as the lease, the stock and the staff handbook.
The central point is simple: accepting cards is not a piece of equipment. It is a contractual relationship between a business entity and a merchant acquirer, payment facilitator or independent sales organisation, often supported by a separate terminal finance agreement. Those relationships do not automatically follow the shop when the owner changes.
Asset sale or share sale: the distinction that matters first
Most small business sales in Bristol are structured as asset sales. The buyer purchases the trade, stock, goodwill and perhaps selected equipment through a new or existing company, while the seller retains the old company. In that structure, the seller's merchant account stays with the seller's company. The buyer cannot simply keep using the terminal and the old account as though nothing has changed.
A share sale is different. The company itself continues, so its contracts generally continue too, including card-processing terms and any terminal lease. That can be convenient, but it also means the buyer inherits the company's contractual history, including liabilities that may not be obvious from the till. A buyer taking shares should inspect the merchant statement, the terminal agreement and any outstanding chargeback or reserve position before completion.
For either structure, the governing documents should say clearly which card-processing contracts are being transferred, terminated or left behind. Ambiguity here tends to surface weeks after completion, when the first settlement fails or a direct debit is taken from an account that no longer belongs to the trading business.
Merchant accounts are approved, not inherited
A buyer should expect to apply for a merchant account in the name of the entity that will actually trade. The acquirer will want to understand the business activity, the expected card turnover, the average transaction value, the nature of sales and the identity of the principals. A café on Gloucester Road and a salon in Redland may both take cards, but their risk profiles are not identical.
Do not assume that a similar-looking business will be approved on the same terms. Seasonal trade, online orders, deposits and large one-off transactions can all affect pricing and conditions. A buyer who needs to open before a busy weekend should start the application early rather than rely on a promised handover of the seller's facility.
The seller, meanwhile, should not leave their merchant account open for a buyer to use informally. That creates confusion over liability, settlement and chargebacks. The clean position is for the seller to terminate or transfer according to the contract, and for the buyer to trade on a properly established account from the first card sale.
Terminal leases have a life of their own
Terminal equipment is often leased or financed separately from the merchant account. The lease may run for a fixed term, may include an early-termination charge, and may require the equipment to be returned in working order. It is not unusual for a seller to believe the buyer will simply take over the payments, only to discover that the finance provider requires a formal assignment or a new agreement.
Buyers should ask for the terminal agreement, the lease schedule, the remaining term and a settlement figure before signing anything. Sellers should do the same, because a lease that is left running after the shop changes hands can become a costly loose end. If the equipment is being sold outright, confirm in writing that the lease has been settled and that the device is not subject to a third-party claim.
There is also a practical security point. A terminal that has been used by the seller should not be handed over with old logins, passwords or administrator settings intact. The buyer needs a clean configuration in the new business name, and the seller needs confidence that their credentials are no longer live.
PCI responsibility follows the trading entity
Card data security obligations do not evaporate at completion. The entity that is trading and accepting cards is responsible for its own PCI DSS compliance, usually through the relevant self-assessment questionnaire and the acquirer's portal. A buyer who adopts the seller's terminal and payment page without updating the account details may find that compliance records, contact addresses and risk assessments still point to the wrong business.
During handover, identify who controls the PCI portal, where the annual questionnaire is filed, and which email address receives compliance reminders. Remove the seller's users where appropriate and add the buyer's. If card data is stored in a till system, booking platform or e-commerce back office, confirm how it will be migrated or deleted. The safest approach is to treat all old credentials as compromised until they have been reset or retired.
Pending settlements and chargebacks do not always stop at completion
Card settlements usually arrive on a known cycle, but the final cycle after a sale can be awkward. The seller may have transactions that settle after completion, while the buyer may be taking payments before their own account is fully active. The sale agreement should allocate responsibility for these amounts clearly, including any fees, reversals and reconciliation costs.
Chargebacks are the sharper issue. A customer dispute can arrive weeks or months after the transaction, and it may concern a sale made under the previous owner. If the merchant account has been closed without a clear post-completion arrangement, the parties can find themselves arguing over evidence and liability. A seller should keep access to transaction records for a sensible period, and a buyer should not accept responsibility for pre-completion disputes unless the price and indemnities reflect that risk.
Where a reserve or rolling holdback is in place, confirm how it will be released and to whom. Ask the acquirer for a final statement and a written position on pending chargebacks. Verbal assurances are not sufficient when money is moving between buyer and seller.
A concise handover checklist
- Identify whether the deal is an asset sale or a share sale, and list every card-related contract affected.
- Obtain the merchant statement, pricing schedule, terminal lease and PCI portal details.
- Confirm the trading entity that will hold the merchant account after completion.
- Ask the acquirer in writing whether the facility can be assigned, transferred or must be closed.
- Calculate any early-termination charge and decide who pays it.
- Agree responsibility for settlements, refunds and chargebacks arising before and after completion.
- Reset terminal credentials, update trading names and remove old users from payment systems.
- Keep transaction records available for dispute deadlines and reconcile the final statement.
For Bristol independents, the commercial lesson is straightforward. A shop can change hands in a afternoon, but a card-processing contract has its own timetable. Treat the terminal as a contract, not a counter accessory, and the handover is far less likely to leave either side exposed.