Authorised Is Not Arrived: Mapping December Card Settlement for Bristol Retailers
Every December, a familiar pattern emerges in independent shops along Gloucester Road and around Corn Street. The terminal reports a healthy day of card takings, the till reconciliation matches, and yet the business current account looks thinner than the sales figures imply. The explanation is rarely a missing payment. More often it is a timing issue: authorisation and settlement are two different events, and in the Christmas run-up the distance between them matters more than at any other time of year.
Authorisation is a promise, settlement is the transfer
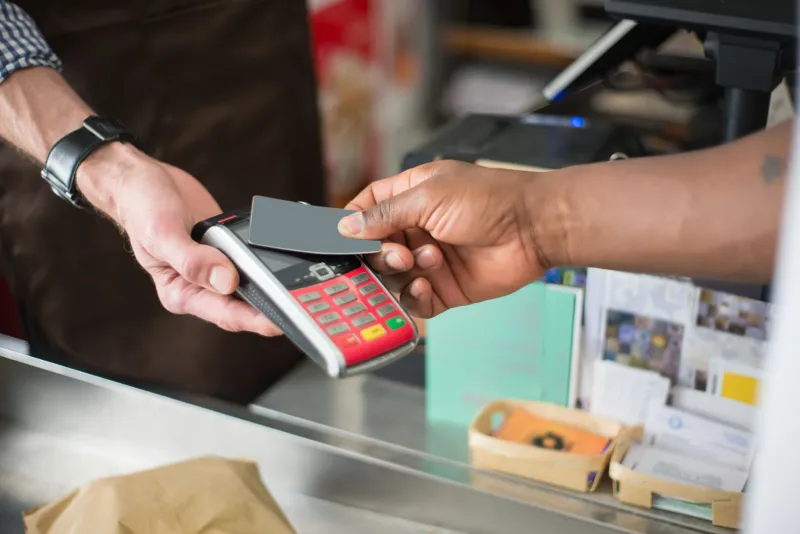
When a customer taps a card, the terminal seeks authorisation from the card issuer. That step confirms the funds are available and reserves them against the customer's account. It is not the same as money arriving in the retailer's bank account. The transaction must first be included in a batch, submitted to the acquiring bank, processed through the card schemes, and then paid out according to the merchant's settlement schedule.
For most Bristol businesses on standard terms, settlement arrives one or two working days after the batch is submitted. Some providers settle next day; others operate a three-day rolling cycle. The precise arrangement is set out in the merchant agreement, and it is worth reading that section before December rather than during it.
A useful distinction is between the terminal's daily total and the acquirer's settlement report. The first records authorisations. The second records what has actually been sent for payment, net of fees, refunds and any chargebacks. Reconciling the two is a discipline, not a formality, and it becomes essential when trading volumes rise.
Cut-off times and the processing calendar
Settlement schedules hinge on a cut-off time. Transactions batched before that point are generally processed the same working day; those after it roll into the next. Cut-offs vary widely. Some providers set them in the early evening, others at midnight, and a few offer near-real-time settlement at a premium. A shop that closes at 6pm may comfortably meet a 10pm cut-off, while a restaurant or late-night venue may not.
This is not a minor administrative detail. A business turning over several thousand pounds a day in December can see a meaningful difference between a 7pm and a midnight cut-off, particularly if the provider treats Saturday as a non-processing day. The practical question is not simply how quickly funds arrive, but which days count as processing days in the provider's calendar.
Weekends, bank holidays and the December calendar
In 2026, Christmas Day falls on Friday 25 December, with Boxing Day on Saturday 26 December and a substitute bank holiday on Monday 28 December. New Year's Day follows on Friday 1 January 2027. For settlement purposes, the working days between those dates are fewer than the calendar suggests.
A transaction authorised on Christmas Eve may not settle until Tuesday 29 December if the provider does not process over the weekend or the bank holidays. Similarly, takings from Saturday 2 January may not land until Tuesday 5 January. Businesses that trade through the period often find that the busiest days produce the slowest settlement.
Bristol's festive calendar adds its own pressures. Late-night shopping evenings, Christmas markets at St Nicholas Market and pop-up trading at Wapping Wharf generate concentrated card volumes, sometimes on days when banking infrastructure is operating a reduced schedule. A pop-up operator with a short lease and weekly supplier payments is especially exposed to these gaps.
Why December cash flow tightens even when sales rise
The counter-intuitive feature of the festive period is that strong sales can coincide with a tighter cash position. There are several reasons. Stock must be bought and paid for before the sales occur. Staff hours rise, and wages are usually paid on a fixed date regardless of settlement timing. VAT and PAYE obligations do not move. Meanwhile, the settlement lag means that the last week of December's takings may not be available until the first week of January.
For a business that relies on weekly supplier terms, this can create a short but sharp working-capital gap. The sales figures are real; the cash is simply in transit. Understanding that distinction allows an owner to plan rather than react.
Planning stock, wages and tax around settlement
A practical approach is to build a buffer equal to the longest expected settlement gap, not the average. If the provider's terms suggest two working days but bank holidays can stretch that to five, plan for five. For many independents, a buffer of seven to ten days of operating costs is prudent through late December and early January.
Three habits help:
- Forecast on a settlement basis, not a sales basis. Project when cash will land, not when the sale was made.
- Separate the terminal report from the bank statement. Reconcile weekly, and investigate any batch that has not settled within the expected window.
- Time large outgoings deliberately. Where possible, avoid scheduling supplier payments or tax reserves against the final week of December's unreconciled takings.
Questions to put to your provider before the festive peak
A short conversation with the acquirer or payments provider in early December can prevent most surprises. The useful questions are specific:
- What is the daily cut-off time, and does it apply at weekends?
- Which days count as processing days over the Christmas and New Year bank holidays?
- Is settlement calculated from the batch date or the transaction date?
- How are refunds and chargebacks deducted, and do they affect the timing of the next settlement?
- Is faster settlement available, and what does it cost per transaction or per month?
- What happens if a batch fails or is submitted after cut-off?
The answers should be recorded in writing. Verbal assurances about "next-day payment" are less useful than a documented schedule.
A simple reconciliation habit
For Bristol retailers and service providers, the most reliable defence against December cash-flow confusion is a modest weekly routine. Download the settlement report, match it to the bank credit, and note any variance. Over a few weeks, the pattern becomes predictable, and predictability is what allows a business to commit to stock, staff and tax payments with confidence.
Card settlement is not instantaneous, and it is not meant to be. It is a scheduled transfer governed by cut-off times, processing calendars and contractual terms. In the Christmas run-up, understanding that schedule is as important as understanding the sales themselves. The takings are real; the task is knowing when they will arrive.