Six Weeks of Trading: Card Processing for Bristol's Christmas 2026 Pop-Ups
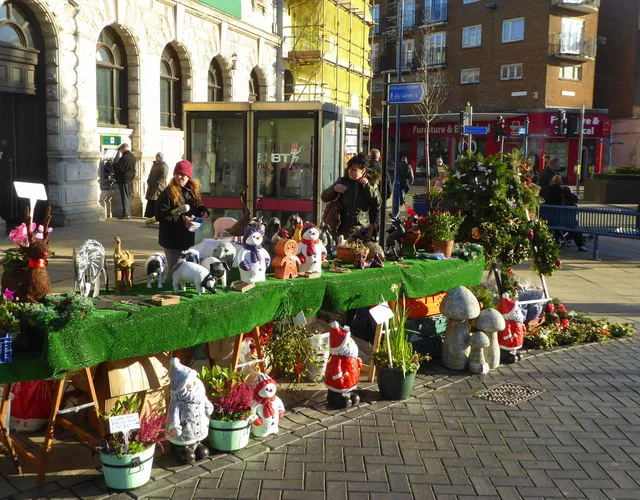
Photo: pam fray , CC BY-SA 2.0, via Wikimedia Commons
The short season has its own cost logic
Bristol's Christmas 2026 trading season will include empty-unit pop-ups in Broadmead, stalls around the Harbourside, one-off shop units in Bedminster, and events at Finzels Reach and Wapping Wharf. Card acceptance is expected at almost every one of them. But a six-week operation should not carry a twelve-month contract without checking. The costs of card acceptance are not only the percentage charged on each sale. They also include terminal hire, authorisation fees, monthly minimum service charges, PCI compliance, chargeback fees, refund handling and connectivity.
For a temporary trader, the commercial question is simple: what will card acceptance cost in total, and does the arrangement fit the length of the trading period? A headline rate that looks cheap can become expensive when a monthly minimum is applied to a low-turnover stall.
Where the costs come from
A merchant account or payment service will usually combine several charges. There is a percentage transaction fee, sometimes with a small fixed authorisation fee per sale. There may be terminal rental or a terminal purchase cost. A monthly minimum service charge is common on traditional merchant accounts: if the month's card turnover is low, the business pays the difference. PCI compliance may carry an annual or monthly fee. Chargebacks and refunds can attract administration charges, and early termination may be charged if a contract is ended before its minimum term.
Pay-as-you-go terminals work differently. They typically have no monthly fee or a low monthly fee, but a higher percentage rate and sometimes a fixed fee per transaction. They can be quick to set up and suitable for low-volume pop-ups, but the trader should check transaction limits, payout timing and whether refunds are supported. A traditional merchant account may offer a lower rate, but the monthly minimum and contract length can outweigh the saving over a short season.
As an illustration, a pop-up taking £10,000 over six weeks might compare a pay-as-you-go rate of 2.75% with a merchant account rate of 1.6% plus a monthly minimum. The merchant account may look cheaper on paper, but only if the monthly minimum is actually exceeded and the contract can be ended cleanly. The right comparison is total cost over the trading period, not the headline percentage.
Portable terminals and connectivity
Temporary sites place practical demands on the terminal. Battery life matters, especially at outdoor events. A SIM-based terminal may be more reliable than Wi-Fi in a listed building or a basement unit. Harbour events and market stalls can suffer from weak signal, so test the location before the first trading day. Some terminals offer offline mode, but offline payments carry risk and should not be treated as a substitute for a reliable connection.
Tap-on-phone acceptance can work for very small operations, but check the transaction limits and receipt options. Whatever the setup, keep a charger, a backup payment method and a clear procedure for what staff should do if the terminal cannot connect.
Refunds and Christmas returns
Card refunds should go back to the original card. They can take several working days to appear, and some providers charge a refund administration fee. Keep the returns policy visible at the stall or till. For event purchases, record an order number or receipt reference so that a refund can be matched to the original sale. If the same terminal is used across several pop-up days or locations, make sure refunds are allocated to the correct trading day.
Do not refund card purchases in cash unless your policy allows it and you can reconcile the till. A cash refund for a card sale can create a mismatch between terminal reports, cash takings and the bank payout.
End-of-day reconciliation
A daily Z report is the starting point. Match the terminal total to the bank payout, then account for refunds, tips, deposits and part-payments. If several staff use the terminal, use separate logins where possible. If an event organiser provides a central till or payment system, clarify who owns the merchant account, who handles chargebacks and how settlement is passed to traders. Keep a simple spreadsheet and reconcile at least weekly. Temporary trading is still trading, and the records need to stand up after the lights go out.
Choosing an arrangement for Christmas 2026
Before signing, ask about contract length, notice periods, monthly minimums, terminal costs, payout speed, refund fees, PCI requirements and chargeback support. Avoid auto-renewal unless you understand how to cancel. If you are trading under an event organiser's umbrella, check their terms carefully rather than assuming your own terminal will be accepted. Get the key terms in writing.
A Bristol checklist before the lights go on
- Estimate card turnover and average sale for the whole season.
- Compare total cost, including monthly minimums and terminal hire.
- Check the contract length and notice period.
- Test connectivity at the actual site.
- Confirm refund and returns procedures.
- Keep daily Z reports and reconcile weekly.
- Clarify who owns the merchant account at shared events.
Christmas 2026 pop-ups can be profitable with the right card arrangement. The risk is not card acceptance itself, but signing a permanent-cost structure for a temporary trading window.