Pay by Bank for Bristol Independents: Where Account-to-Account Payments Make Commercial Sense
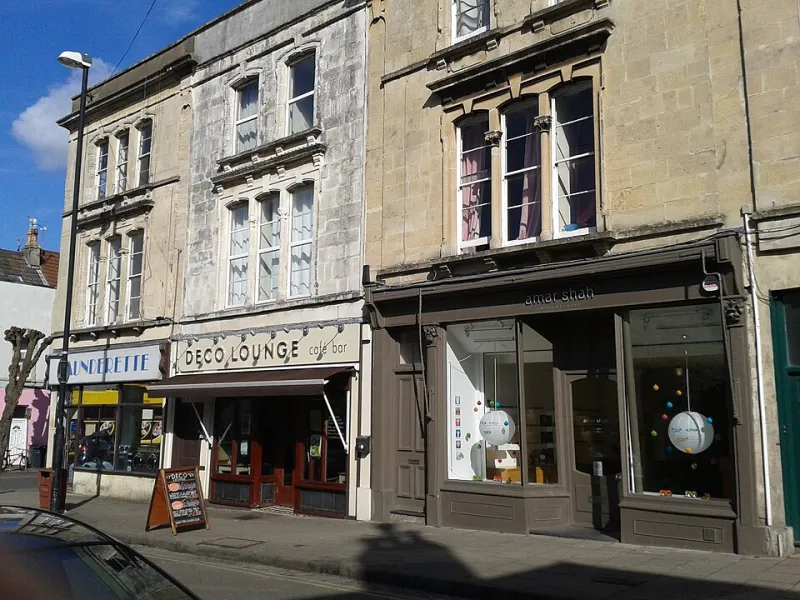
Photo: Virginia Knight , CC BY-SA 2.0, via Wikimedia Commons
Pay by Bank is now part of the payment mix in many UK shops, but it is not a simple card replacement. For Bristol independents, the question is commercial: which transactions justify an account-to-account payment, and which still belong on a card terminal? This guide compares the two on cost, settlement and customer experience, and identifies where Pay by Bank can earn its place alongside cards in 2026.
What Pay by Bank actually does
Pay by Bank uses Open Banking to move money directly from a customer's bank account to the business. The customer authorises the payment through their banking app, often by scanning a QR code, approving a prompt or following a payment link. The payment usually travels through Faster Payments, although the provider's own settlement timing should always be checked.
It is not a card payment. There is no card number, no card scheme and no terminal reading a chip or contactless card. That distinction matters for fees, disputes and the customer journey.
The fee comparison in practice
Card processing costs are usually made up of interchange, scheme fees and the acquirer's margin. A quoted card rate may also exclude terminal rental, gateway charges, PCI compliance support or minimum monthly fees. Pay by Bank avoids card scheme costs, but the provider still charges for the payment, the integration and sometimes account verification. A lower headline rate is not automatically a lower total cost.
The transaction profile matters more than the advertised percentage. A fixed Pay by Bank fee can look expensive against a three-pound coffee, while a percentage-based fee can be attractive on a two-thousand-pound bike or a large building job. The right comparison is the effective monthly cost across the actual mix of transactions, not a single rate card.
Settlement, refunds and disputes
Card settlements often arrive on a next-day or two-day cycle, depending on the provider. Pay by Bank can settle quickly because the underlying payment rail is fast, but the merchant provider may hold or batch payments. Businesses that rely on immediate cash flow should confirm the exact timing in writing.
Refunds and partial refunds also need scrutiny. Card terminals usually have a familiar refund process. Pay by Bank refunds are less standardised across providers, so the merchant should ask how a return, cancellation or deposit refund is handled and how long it takes.
Disputes work differently too. Card chargeback rules do not apply in the same way to account-to-account payments. Disputes are generally handled through the bank and the provider, with evidence of authorisation and communication. That can be simpler in some cases and less familiar in others. Customers may also value the protection associated with credit cards, which Pay by Bank does not replicate.
Where Pay by Bank fits Bristol businesses
High-ticket independent retailers are a natural fit. A Bristol bike shop, furniture retailer, jeweller or gallery may handle transactions where a card percentage fee is meaningful. Offering Pay by Bank as an option at the point of sale or by payment link can reduce processing cost without removing the card terminal.
Tradespeople and contractors also have a strong case. Deposits, stage payments and final invoices are often large, and customers are already used to paying trades by bank transfer. A Pay by Bank link can formalise that process, reduce the risk of incorrect bank details and avoid card fees on substantial jobs.
Invoice-heavy service providers, such as professional services firms and specialist contractors, can use Pay by Bank for one-off invoices and repeat clients. It can sit alongside direct debit or card payment links, giving the customer a familiar banking-app approval step.
Where card still wins
Card remains the better default for small-ticket, high-volume retail. Contactless is fast, familiar and accessible, and customers expect it at the counter. Card also supports credit payments, international visitors, tipping flows and integrated point-of-sale systems that staff already understand.
Card is also more resilient in weak connectivity. Pay by Bank generally requires an internet connection and a customer's banking app, so it is not a fallback when broadband or mobile data fails. Offline card modes have limits, but they still offer a more established procedure than an account-to-account payment in a dead spot.
A practical evaluation checklist
Before adding Pay by Bank, calculate the effective cost of current card processing, including terminal rental, gateway fees and chargebacks. Then model the new provider's fee against the real average transaction value and the share of high-value sales. Confirm settlement timing, refund handling, dispute process and customer support. Ask whether the payment can be presented as an option rather than a default, and train staff so the customer is not left comparing two unfamiliar journeys at the counter.
For most Bristol independents, Pay by Bank is best treated as a targeted complement: useful for large transactions, deposits and invoices, while cards continue to carry everyday retail. The commercial case is strong where the ticket size is high and the customer is comfortable with banking-app approval. It is weaker where speed, familiarity and small-ticket convenience matter most.